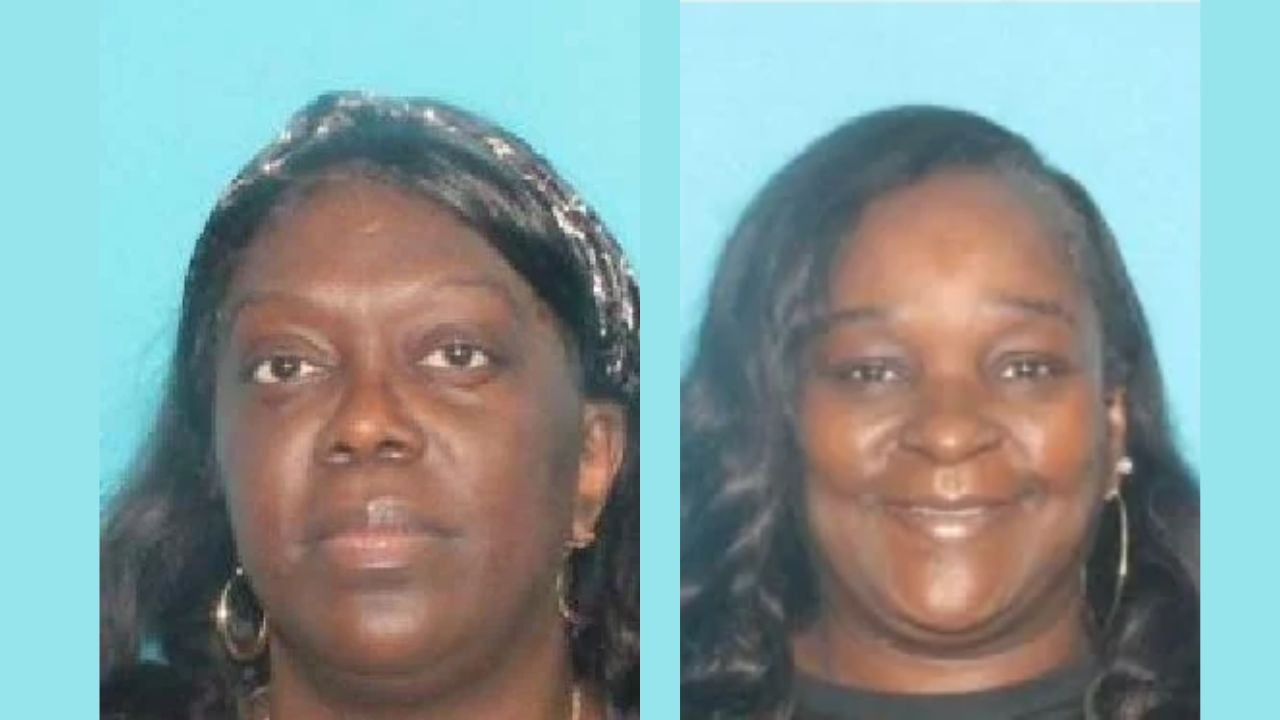
Two North Carolina tax preparers falsely claimed that federal income taxes had already been withheld from their customers’ earnings, producing larger refunds and allowing them to collect excessive fees, according to federal prosecutors.
Chowan Watson, 55, of Rocky Mount, has pleaded guilty to aiding and assisting in the preparation of a false tax return. The U.S. Attorney’s Office for the Eastern District of North Carolina announced her plea on October 28, 2026.
Her admission follows an earlier guilty plea by Angela Dickens, 54, who operated the same tax preparation business. Prosecutors say the two women submitted hundreds of fraudulent federal returns between 2017 and 2023 through Empire Tax Service, later renamed K&J Tax Service.
The government estimates approximately $3.9 million in tax losses across the operation. Both women are awaiting sentencing and have agreed to pay restitution to the Internal Revenue Service.
False 1099 Withholding Entries Made Customer Refunds Larger
Rocky Mount Tax Preparer’s $3.9M Fraud Empire Crumbles, She Confesses Guilt ⚖️💥👍🎯🔐
“Watson and Dickens didn’t just bend the rules—they broke the door wide open,” said U.S. Attorney Ellis Boyle. “For years, they engineered a scheme that faked withholdings, pumped up refunds, and drained the U.S. Treasury of nearly four million dollars. They preyed on the trust of hardworking Eastern North Carolinian taxpayers and twisted a legitimate tax preparation service into a personal profit machine. This case sends a clear message to all fraudsters: if you cheat the system and exploit your clients, we will expose your scheme, pursue you, and prosecute you. Cheaters. Never. Win.”
Read full press release at: https://t.co/01zjZkjglm
— USAO_EDNC (@USAO_EDNC) October 28, 2026
The fraudulent returns contained inflated amounts in a category identified by prosecutors as “Other 1099 Withholding.” Certain Forms 1099 report federal income tax already withheld from payments such as interest, dividends, retirement distributions or other income.
The IRS instructions for Form 1040 explain that federal income tax withheld from Forms 1099 generally belongs on line 25b. Those amounts count toward the tax a person has already paid, so a return showing more withholding than actually occurred can produce a refund larger than the taxpayer is entitled to receive.
Watson’s Guilty Plea Follows Dickens’s Earlier Admission
Chief U.S. District Judge Richard E. Myers II accepted Watson’s guilty plea to one count of aiding and assisting in the preparation of a false tax return. Her federal case is numbered 5:26-CR-125-M in the Eastern District of North Carolina.
On August 4, the Justice Department announced that Dickens had pleaded guilty to the same type of federal tax offense. Her separate case is numbered 5:26-CR-126-M-1, and the earlier announcement identified her as an operator of Empire Tax Service alongside at least one co-conspirator.
Each woman faces a statutory maximum sentence of 36 months in federal prison. Dickens was expected to be sentenced in November 2026, while Watson’s sentencing was anticipated later in the year, according to their respective Justice Department announcements.
The offense of willfully assisting in the preparation of a materially false tax return is addressed under 26 U.S.C. § 7206(2). IRS Criminal Investigation conducted the investigation.
What Taxpayers Should Check Before Signing a Return
The IRS advises taxpayers to review their returns before signing, even when they pay a professional to prepare them. Customers should compare the federal withholding claimed on their returns with the amounts shown on their actual W-2 and 1099 forms, paying particular attention to unfamiliar withholding entries.
The agency also advises avoiding preparers who base their fees on a percentage of the refund or promise an unusually large payment before reviewing the taxpayer’s financial records. Paid preparers must sign the returns they prepare and include a valid Preparer Tax Identification Number, or PTIN.
Taxpayers should also check that the bank account listed for direct deposit belongs to them and retain a complete copy of the filed return. Someone who discovers suspicious withholding amounts should compare the filed information against original tax documents and preserve any communications with the preparer.
Suspected misconduct can be reported through the IRS’s tax return preparer complaint service, including Form 14157. An individual whose preparer altered tax information, diverted a refund or filed a return without authorization may also be eligible to request account corrections through Form 14157-A, subject to the IRS’s supporting-documentation requirements.