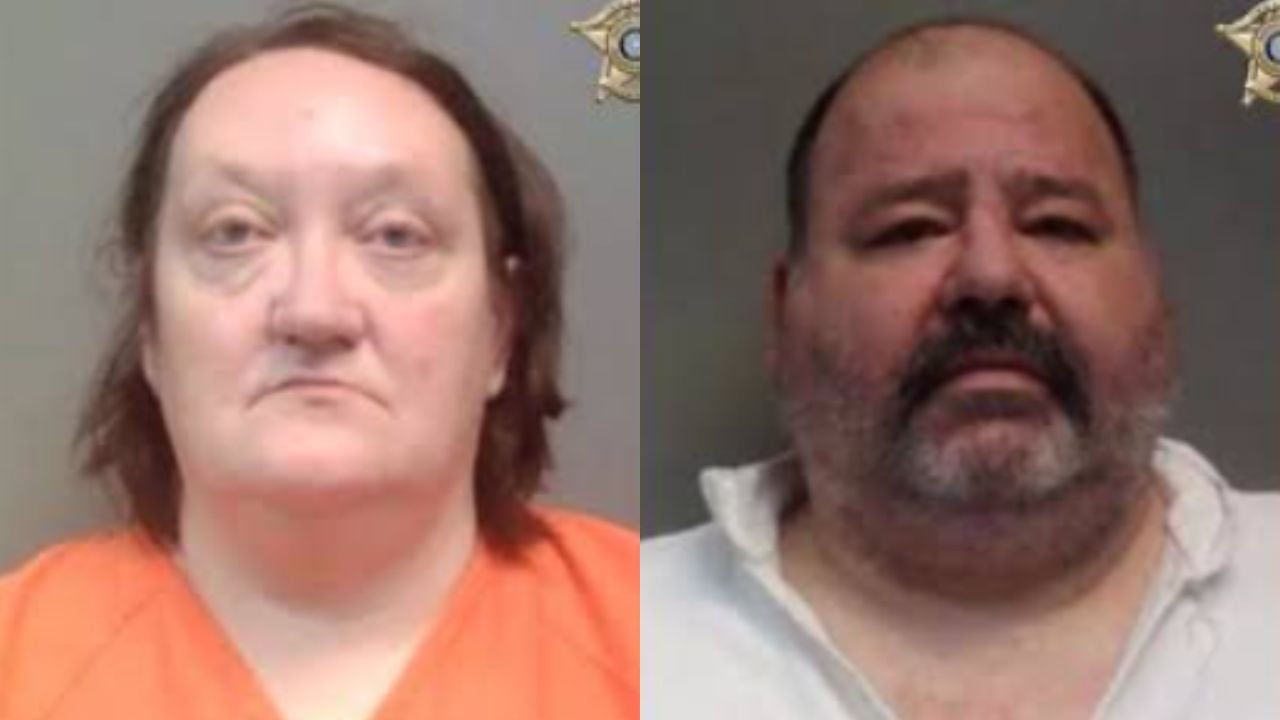
A church treasurer and her husband in East Texas were arrested after a review of financial records uncovered more than $57,700 in debit-card transactions investigators say their congregation never authorized.
Sharon Conn, 52, and Daniel Conn, 49, both of Kirbyville, were taken into custody on Oct. 7, 2026, following an investigation by the Jasper County Sheriff’s Office.
Sheriff Chuck Havard referred a possible theft involving the church to Investigator A.J. Noel on Sept. 21.
Sharon, who served as treasurer, faces a felony charge involving the alleged misuse of money entrusted to her. Daniel faces a separate felony charge concerning unauthorized debit-card use.
Invoices and Receipts Linked the Couple to Disputed Spending
According to the Jasper County Sheriff’s Office, Noel examined approximately two years of bank statements with assistance from church members. Investigators also reviewed invoices and receipts that they said connected Sharon and Daniel to the disputed spending.
After examining the financial evidence, detectives interviewed both defendants. The sheriff’s office reported that the couple acknowledged using the church’s debit card without the congregation’s knowledge or consent.
Havard condemned the alleged misconduct, saying, “Stealing from anyone is bad enough, but stealing from a church is especially reprehensible.” He also praised Noel’s investigative work in bringing the case to the point of arrest.
The Church Treasurer and Her Husband Face Different Felony Charges
Sharon Conn was charged with misapplication of fiduciary property or property of a financial institution, a third-degree felony under Texas Penal Code §32.45.
The statute applies when someone intentionally, knowingly or recklessly misapplies property held in a fiduciary capacity in a way that creates a substantial risk of loss. Misapplication involving property valued at $30,000 or more but less than $150,000 is classified as a third-degree felony.
Daniel Conn was charged with debit card abuse under §32.31 of the same chapter. The offense covers several forms of fraudulent card activity, including using a card without the effective consent of the person or organization entitled to authorize its use. The charge announced against Daniel is classified as a state jail felony.
Under Texas sentencing law, a third-degree felony generally carries a prison term of two to 10 years, while a state jail felony ordinarily carries confinement ranging from 180 days to two years. Both classifications can also carry fines of up to $10,000.
Those are statutory punishment ranges, not sentences imposed on either defendant. The charges remain allegations, and Sharon and Daniel Conn are presumed innocent unless proven guilty in court.
How Churches Can Protect Their Funds From Unauthorized Spending
The National Council of Nonprofits recommends internal financial controls that divide responsibility for authorizing transactions, handling funds and reconciling accounts. Separating those duties reduces the risk of spending going unchecked by anyone outside the purchasing process.
For churches using debit cards, safeguards can include limiting authorized cardholders, establishing spending restrictions and requiring itemized receipts that document the church-related purpose of each purchase.
Finance committee members or other designated reviewers can obtain statements directly from the bank and compare transactions against approved expenses. Unfamiliar merchants, repeated charges outside the organization’s usual operations and payments without supporting documentation warrant closer examination.
If suspected unauthorized spending is discovered, church leaders should preserve original bank statements, receipts and relevant communications while securing affected cards and accounts. The financial institution and law enforcement should be notified promptly. An independent accounting review can help determine the scope of disputed transactions and preserve documentation for investigators.